Can Minors Pay Income Tax in India? Rules Parents Should Know
Children today are exploring new ways to earn money through social media, entertainment, competitions and independent ventures.
However, earning at a young age also brings financial responsibilities. In India, income tax rules apply to minors too, depending on their income sources and applicable exemptions.
Under the Income-tax Act, 1961, a minor is generally a person below 18 years.
Although minors can earn income, the law usually clubs their taxable income with that of a parent.
A minor can receive two broad categories of income. Earned income includes money received through personal skills, talent, manual work, salaries or business activities.
For example, prize money from competitions and earnings through creative work fall into this category.
Unearned income includes gifts, bank interest, fixed deposit returns and investment income. Parents or grandparents may also transfer assets or money to children, generating income in their names.
Yes, minors can have tax liabilities. Under Section 64(1A), income earned by a minor is generally added to the income of the parent with the higher income. However, certain exceptions apply.
Parents can claim an exemption of up to ₹1,500 per minor child annually under Section 10(32), subject to applicable conditions.
If both parents earn, the income is generally clubbed with the income of the parent earning more.
In cases of separation, it is usually included in the income of the parent maintaining the child.
However, income earned through personal skills, talent or manual work is taxable separately in the minor’s hands. The same applies to eligible minors with disabilities covered under Section 80U.
Children winning television competitions, knowledge contests or talent shows may also attract income tax.
Under Section 115BB, specified winnings are generally taxed at a flat rate of 30%, along with applicable cess. The effective rate is 31.2% with a 4% health and education cess.
Parents can invest in fixed deposits, post office schemes, mutual funds and equities in a minor’s name, subject to applicable procedures.
A Demat account can also be opened for a minor through a guardian.
However, investment income may be clubbed with the parent’s income under applicable tax provisions. The ₹1,500 exemption is also subject to the relevant tax regime and conditions.
A minor filing an independent return through a representative assessee may require a PAN card, income records, bank account details, investment statements and active mobile and email details.
Parents and guardians should understand these provisions before filing returns for children.
Proper reporting and timely compliance can help avoid tax complications as young earners become financially independent.
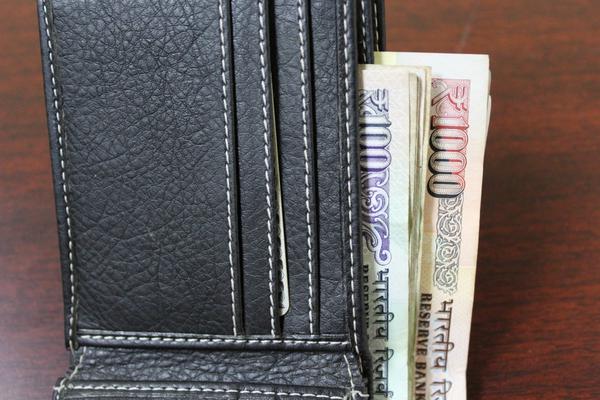
Image from Pxhere (Free for commercial use / CC0 Public Domain)
Image published on February 12, 2017
You may also like
Image Reference: https://pxhere.com/en/photo/692233
Recent Posts
- Young Indians at Risk: Understanding Stroke
 Regular health check-ups and healthier habits can also help young adults reduce their stroke risk.
- Can Minors Pay Income Tax in India? Rules Parents Should Know
 Parents and guardians should understand these provisions before filing returns for children.
- NIC Winter Internship 2026: Apply for ₹10,000 Stipend
 Students pursuing BE/BTech, ME/MTech, MCA and relevant computer science programmes are eligible to apply.
WeRIndia – A News Aggregator
Visit werindia.com for all types of National | Business | World | Politics | Entertainment | Health related news and much more..
Leave a Reply