Smart Ways to Manage Medical Expenses
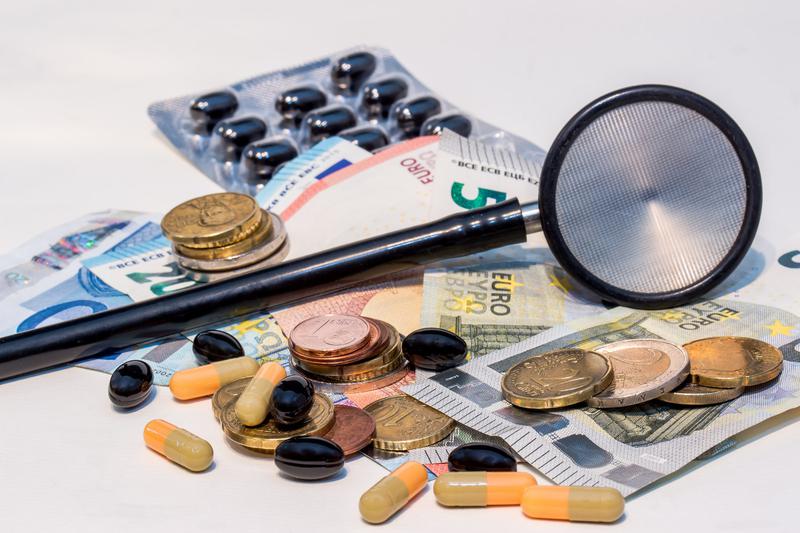
Unexpected medical expenses can disrupt even a carefully planned household budget.
When a ₹5 lakh hospital bill leaves a ₹3 lakh shortfall after insurance settlement, families may feel pressured to exhaust their savings or borrow at high interest rates.
However, a balanced financial strategy can help cover the remaining cost while protecting long-term security.
According to Jose Peter, Co-Founder and CEO of Arogya Finance, patients should assess their immediate obligations alongside the financial demands of recovery.
Here are seven practical ways to manage an unpaid hospital bill without draining your savings.
Calculate future medical expenses
Before arranging the ₹3 lakh shortfall, estimate the costs of medicines, follow-up consultations, rehabilitation and potential income loss. Moreover, consider whether the treatment involves a one-time procedure or a condition requiring long-term care. Keeping enough cash for recovery can prevent further financial stress.
Review the hospital bill and insurance settlement
Check the itemised hospital bill against the insurer’s settlement letter. Look for billing errors, room rent restrictions and non-payable expenses. If you identify discrepancies, raise them with the hospital or insurer before paying the outstanding amount.
Explore interest-free medical instalments
Ask the hospital whether it offers zero-interest medical EMIs. However, verify processing fees, repayment terms and the total treatment cost before agreeing. Choose instalments that comfortably fit your monthly income.
Compare fixed deposit options
If you have a fixed deposit, compare the cost of premature withdrawal with a loan against the deposit. Borrowing may preserve interest earnings when the deposit approaches maturity. Conversely, breaking the FD could prove cheaper for longer repayment periods, depending on the applicable terms.
Consider partial EPF withdrawals carefully
Eligible salaried employees may qualify for partial Employees’ Provident Fund withdrawals for medical needs, subject to applicable rules. However, processing can take time, making this unsuitable for urgent discharge payments. Withdrawals also reduce retirement savings.
Combine savings with affordable borrowing
Rather than exhausting your entire cash reserve, consider using part of your liquid savings alongside lower-cost financing. This approach can cover the immediate bill while preserving funds for household expenses and recovery.
Protect long-term investments
Avoid liquidating investments earmarked for major life goals unless other options prove unsuitable. Instead, maintain an emergency fund and review whether your health insurance provides adequate coverage. A suitable super top-up policy may also help manage future medical expenses, subject to its terms.
Ultimately, handling a ₹3 lakh medical shortfall requires careful planning rather than rushed borrowing.
Reviewing the bill, comparing financing options and protecting emergency savings can help families manage treatment costs without compromising their financial future.
Image from Pxhere (Free for commercial use / CC0 Public Domain)
Image published on March 19, 2017
You may also like
Image Reference: https://pxhere.com/en/photo/1201447
Recent Posts
- HealthFab: Sustainable Period Care
 HealthFab was founded by Kiriti Acharjee, Saurav Chakraborty and Satyajit Chakraborty, all from Assam.
- Smart Ways to Manage Medical Expenses
 Unexpected medical expenses can disrupt even a carefully planned household budget. When a ₹5 lakh hospital bill leaves a ₹3 lakh shortfall after insurance settlement, families may feel pressured to…
- YLEM: Turning Waste into Sustainable Design
 New Delhi-based design and research studio that transforms discarded materials into valuable, functional products.
WeRIndia – A News Aggregator
Visit werindia.com for all types of National | Business | World | Politics | Entertainment | Health related news and much more..